The moment you take your first paid gig, you've started a business, whether or not you filed anything. That surprises most people, and it leads to the next question every side hustler eventually asks: "Do I need an LLC?" The honest answer is that it depends on what could go wrong, how much you have to lose, and what you're willing to manage. An LLC isn't a badge of seriousness. It's a tool with one main job, and it's worth knowing what that job is before you pay for it.
What You Already Are: A Sole Proprietor
If you earn money on your own and haven't set up anything else, the default label is sole proprietor. There's no filing to make it official. You and the business are legally the same person, which has a few practical effects:
- It's free and instant. No formation paperwork, no annual state filing, no separate account required to begin.
- Taxes are simple. Business income and expenses typically land on your own personal return, rather than on a separate business return.
- Your own name is the business. If you want to trade under a different name, many places ask you to register that name, but that's a naming step, not a new legal entity.
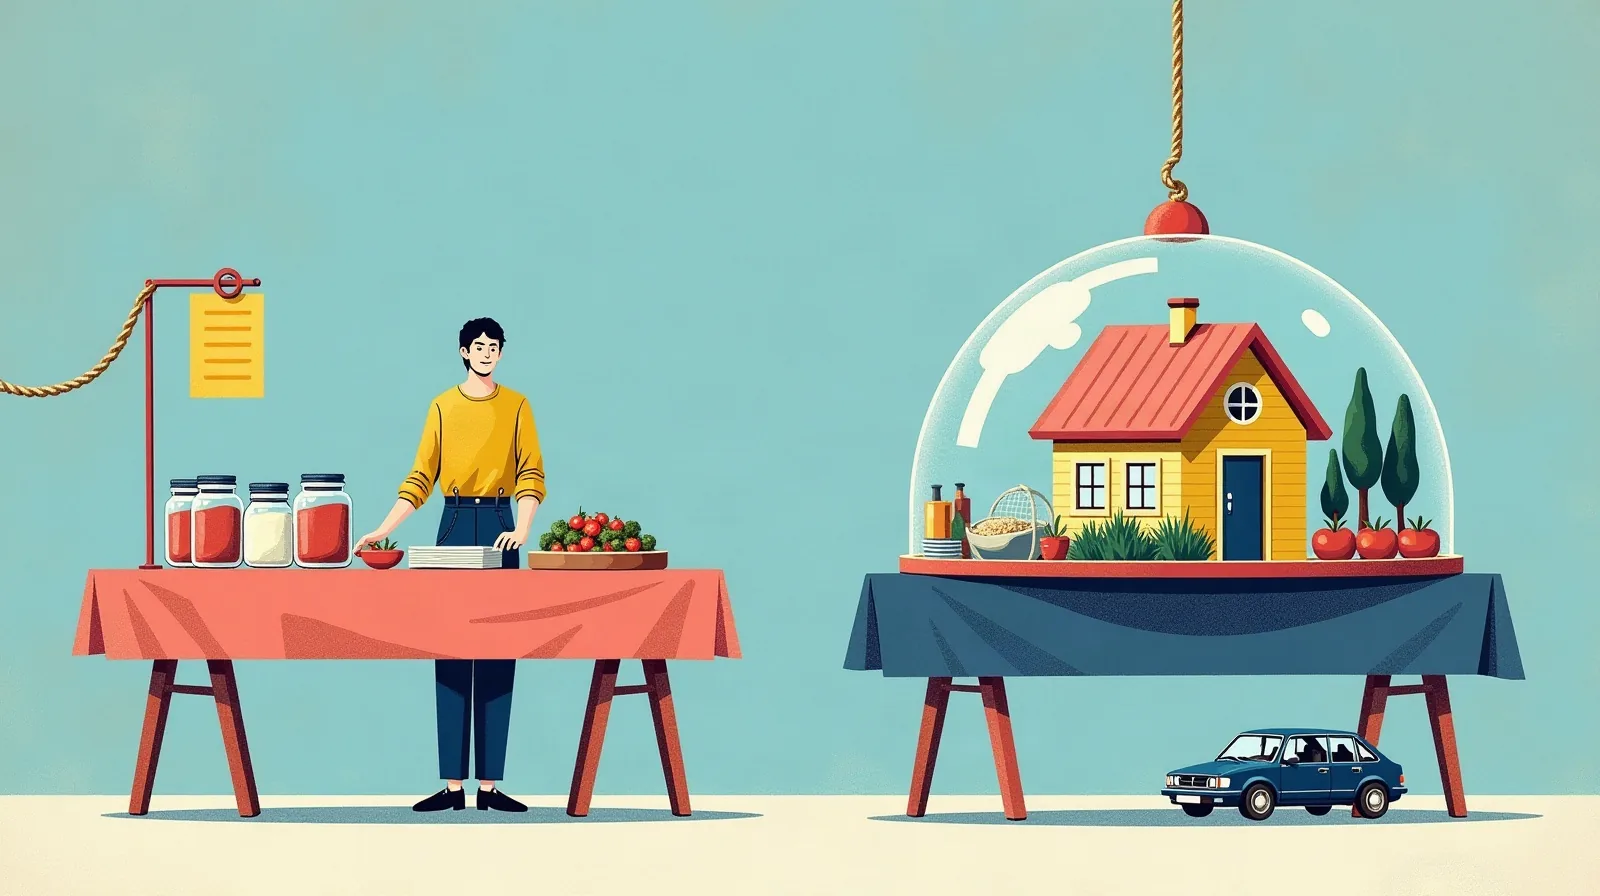
- Everything you own is in play. Because there's no legal wall between you and the business, a business debt or lawsuit can reach personal assets.
That last point is the whole reason the LLC conversation exists. Everything else is detail.
What an LLC Actually Does
A limited liability company is a separate legal entity you create by filing with your state. Its core purpose is liability separation: in many situations, the company's debts and legal problems stay with the company rather than following you home to your house, your savings, and your car.
It also comes with some side effects worth knowing about:
- Ongoing costs. Most states charge to form one, and many charge again every year or two to keep it active. Amounts vary widely by state, so look up yours.
- Paperwork and upkeep. Annual reports, a registered address, and a record of company decisions are common requirements.
- Usually the same tax treatment. A one-owner LLC is commonly taxed the same way as a sole proprietor unless you elect something different, so don't expect it to shrink your tax bill by itself.
- A separate bank account becomes non-negotiable. The separation only holds if you actually treat the company as separate.
What an LLC Does Not Do
This is where the marketing gets ahead of reality. An LLC is not a force field, and several common beliefs about it are wrong:
- It doesn't protect you from your own mistakes. If you personally cause harm, such as injuring a customer or giving damaging advice, you can still be held responsible for your own actions.
- It doesn't replace insurance. Liability coverage pays for claims; an LLC only affects whose assets can be reached. Many side hustlers do better with the right coverage than with a filing alone.
- It doesn't make loans safer for you. Lenders and landlords often ask for a personal guarantee from a small owner, which puts you back on the hook.
- It doesn't survive sloppy habits. Mixing personal and business money, or ignoring required filings, can give a court a reason to disregard the separation.
- It doesn't cut self-employment tax on its own. That tax follows your earnings, not the type of entity.
How Much Risk Does Your Side Hustle Really Carry?
The value of liability separation scales with what could realistically go wrong and what you stand to lose. Ask yourself:
- Can someone be hurt or lose property because of what you do? Working in people's homes, handling food, caring for children or pets, or doing physical work all carry more exposure than writing, design, or online tutoring.
- Do you sign contracts that could be expensive to break? Larger client agreements and equipment leases raise the stakes.
- Do you have meaningful assets to protect? Home equity and savings are worth guarding; a thin balance sheet has less to lose.
- Do you have employees or helpers? Other people acting on your behalf expand your exposure.
- Is the income growing? A hobby-level trickle and a full second paycheck are different risk profiles.
Low exposure and modest income often point toward staying a sole proprietor and covering the gaps with insurance. High exposure, real assets, or fast growth make the case for an LLC much stronger.
A Practical Way to Decide
You don't have to choose forever on day one. A common, sensible path looks like this:
- Start as a sole proprietor. Prove the idea works before paying to formalize it.
- Open a separate bank account immediately. It costs little, simplifies your taxes, and builds the habit an LLC would require anyway.
- Check your insurance. Ask your insurer whether your home or auto policy excludes business activity, and price a small business liability policy if it does.
- Revisit when something changes. A bigger client, a new hire, a physical product, or a jump in income is a good moment to reconsider.
- Look up your own state's rules. Formation steps and annual costs differ a lot, and a short consult with a local accountant or attorney can be worth it before you file.
Common Mistakes to Avoid
- Forming an LLC and then mixing the money. Paying personal bills from the company account weakens the very protection you paid for.
- Assuming the LLC replaces insurance. It answers a different question.
- Waiting until after a problem. Setting up protection after a claim is filed rarely helps with that claim.
- Forgetting renewal filings. An LLC that lapses can lose its good standing and its benefits.
- Copying someone else's setup. A friend's structure fits their risk, state, and income, not necessarily yours.
Choosing a structure isn't a test of how serious you are about your side hustle. It's a risk decision, and it can change as the work grows. Start simple, protect what matters, and upgrade when your exposure says it's time.