Money is one of the few life skills we expect kids to somehow absorb by osmosis. We talk to them about manners, safety, and homework, but the mechanics of earning, saving, and spending often go unspoken until they're suddenly adults with a paycheck and no map. The good news: teaching money isn't a lecture you deliver once. It's a series of small, age-appropriate habits, each one building quietly on the last.
Here's what that looks like as a child grows — and why the lessons that stick are almost never the ones you plan.
Toddlers and preschoolers: coins, patience, and waiting
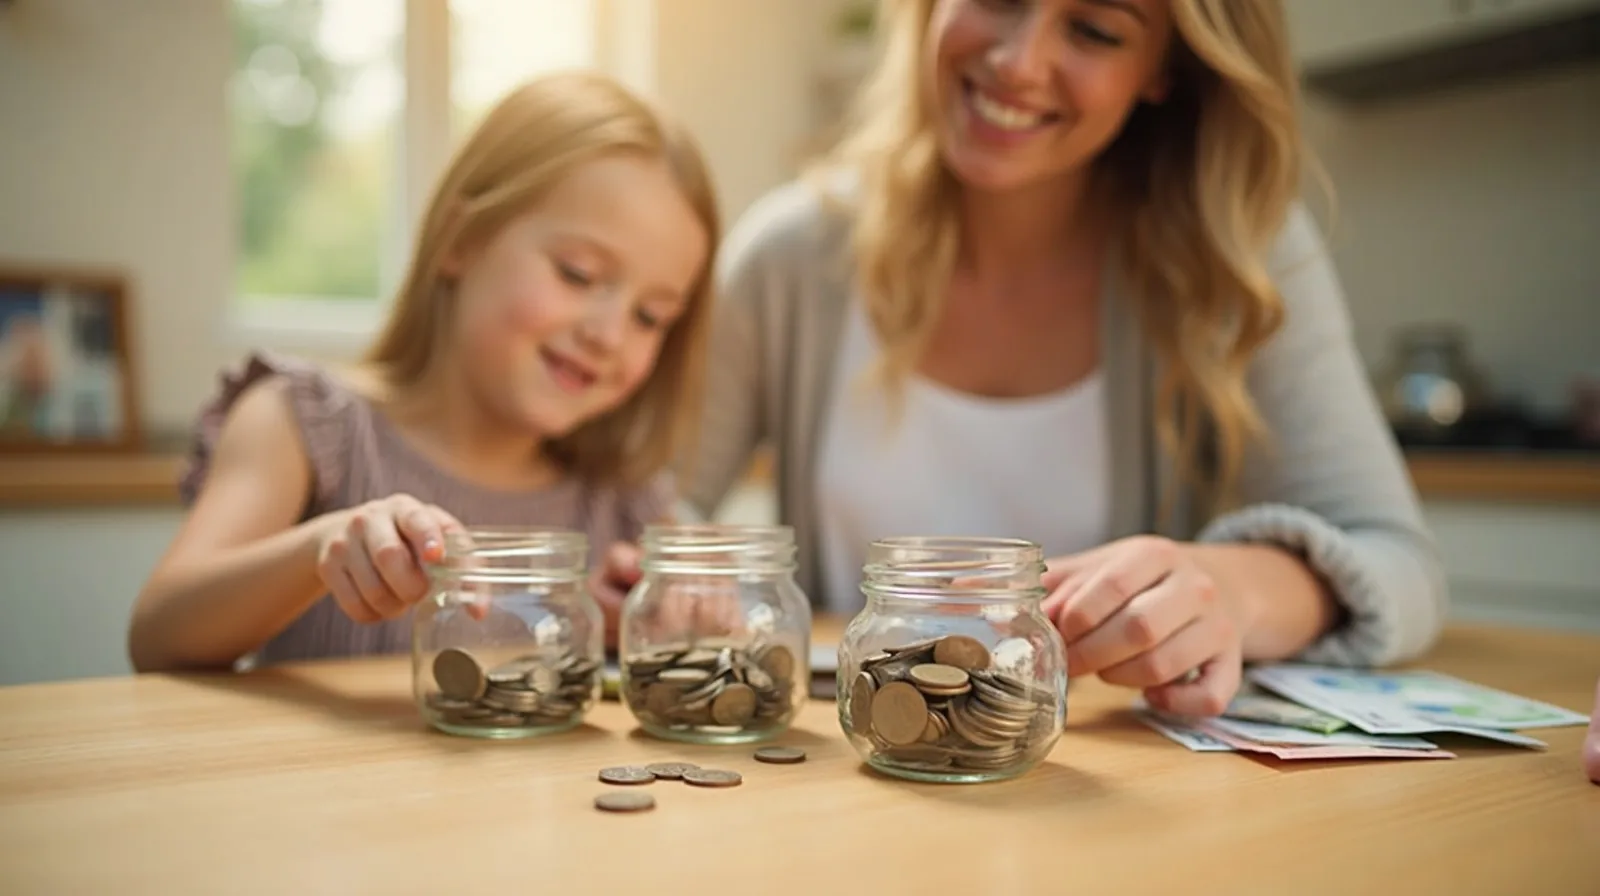
At this age, the concept of money is far too abstract, but two of its foundations are not. The first is that coins and bills are objects with names and value — sorting them, stacking them, and naming them is genuinely useful play. The second, and more important, is patience. Learning to wait — for a turn, for a treat, for tomorrow — is the earliest form of delayed gratification, and delayed gratification is the muscle behind every saving decision they'll ever make. A clear jar they can watch fill up teaches more than any explanation, because they can literally see “more” accumulate over time.
Early elementary: allowance, jars, and the idea of earning
Somewhere in these years, money becomes real: kids notice that things cost something and that the supply isn't infinite. This is the age for the classic three-jar system — one jar to save, one to spend, and one to give. Splitting money the moment it arrives makes each purpose concrete and turns abstract virtues like generosity and patience into physical acts.
It's also when the question of allowance arrives, and reasonable parents disagree about it. There are three broad camps:
- Tied to chores. Money is earned through work, reinforcing the link between effort and reward. The risk is that kids may start expecting payment for every basic contribution to the household.
- A baseline, no strings. A regular sum, given simply because managing money is a skill worth practicing. The risk is that it can feel disconnected from the idea that money is earned.
- A hybrid. A small baseline for practice, plus the chance to earn extra through bigger, optional jobs. This is where many families land, because it captures a bit of both lessons.
None of these is the “correct” answer. What matters more than the model is consistency — a system your child can predict, and that you can actually stick to.
The value of cheap mistakes
Here is the hardest part for most parents: letting kids spend their own money on something you know is a bad idea. The impulse to intervene is strong, but a small purchase that disappoints — a toy that breaks by dinner, a game that's boring after a day — is one of the most powerful lessons available, and it will never again be this inexpensive. A regret felt over a small sum today is tuition for the far larger decisions coming later. If you rescue every choice, the only lesson learned is that someone else absorbs the consequences.
Tweens: wants versus needs, and bigger goals
As kids approach their teens, they can handle more nuance — and they encounter far more marketing. This is the season to talk openly about wants versus needs, not as a rule but as a genuine question worth asking before a purchase. It's also the age when comparison shopping clicks: checking whether the same item costs less elsewhere, and noticing that the flashier version isn't always the better value.
Most importantly, tweens can hold a goal in mind. Saving for something meaningful — something that takes weeks or months of patience — teaches more about money than a dozen conversations. The waiting is the lesson. When they finally buy the thing they saved for, they've felt the full arc of earning, delaying, and choosing, and that memory lasts.
Teens: accounts, a first job, and a real paycheck
Teenagers are ready for the grown-up version. The idea of a bank account — a safe place money lives, tracked to the cent — introduces the habit of watching a balance rather than a pile of cash. A first job, formal or informal, does something no allowance can: it connects hours of real effort to money earned, and makes every subsequent spending decision quietly more considered.
With earnings comes the chance to budget a paycheck — deciding, before the money is spent, how much goes toward saving, spending, and longer-term goals. This is also the moment to talk honestly about the real cost of borrowing: that money borrowed usually has to be paid back with more on top, and that a small sum borrowed carelessly can quietly grow into a much larger burden. You don't need numbers to make the point — just the principle that borrowing is never free.
The lesson you're always teaching
Underneath every stage sits the quietest teacher of all: you. Kids absorb far more from watching how you handle money — whether you plan, whether you pause before buying, how you talk about it under stress — than from anything you formally explain. You don't have to be perfect, and pretending to be usually backfires. Narrating your own real decisions, including the trade-offs and the occasional regret, is often the most honest and durable lesson of all.